AI consulting · Insurance
AI consulting for insurance carriers, MGAs and brokers
Native helps insurance carriers, MGAs and brokers put AI agents into submissions, endorsements, underwriting and claims, inside the systems they already run. Pilots go live in weeks, and whole departments run AI native within months. At TIE, a US transportation MGA, 74% of endorsement decisions now need no underwriter.
 Featuring insights fromShaun Devan · Founder & CEO
Updated · 4 min read
Where AI has an impact in insurance
Submission intake and triage
Every new-business pack read on arrival, sorted by line and appetite, and pre-filled for the underwriter.
Endorsements and mid-term changes
Routine policy changes checked against the rules and decided in under a minute.
Underwriting pre-analysis
Loss runs, MVRs and safety records summarised, with the reasoning for each flag written out.
Document extraction
ACORD forms, loss runs, licences and schedules read accurately, whatever the format or scan quality.
Compliance and risk checks
Federal safety, sanctions and licensing databases queried mid-process, with every result on record.
Claims intake
First notice of loss captured, classified and routed with the policy and coverage already attached.
Renewals
Renewal files assembled ahead of time, with changes since last term highlighted for the underwriter.
Agent and broker service
Status questions answered from the policy record, so the team stops chasing emails.
Why speed decides who wins in insurance
Retail agents send the same file to several markets, and the first usable quote tends to win the business. Turnaround is revenue, and most insurers lose it in the queue rather than in the underwriting itself: reading a submission or an endorsement takes minutes, but the file waits hours or days for someone to pick it up.
That is where AI has the most impact. Agents read every document the moment it lands, run the checks an underwriter would run, and either settle the decision or hand a person a file that is already analysed. The underwriter's time goes to the cases that need judgement.
What the agents decide, and what stays with underwriters
Every engagement starts by drawing this line with your underwriting leads. The agent's authority is written down, and every action it takes is on record.
| Work | Agent | Underwriter |
|---|---|---|
| Routine endorsements (add a driver, a vehicle, a certificate holder) | Checks against the rules and decides | Sees the record, overrides if needed |
| New-business submissions | Reads the whole pack, runs the checks, pre-fills the decision | Makes the call |
| Missing or unreadable documents | Flags the gap the same day and drafts the request | Not involved |
| Risk outside appetite or guidelines | Refers with the reasoning written out | Decides |
What an AI engagement in insurance looks like
We start with the queue, not the technology. In the first two weeks we map how submissions and endorsements move today: where they arrive, which documents come with them, which checks are made, and where files wait. That map ranks the workflows by impact.
The first agent goes into production within weeks, usually on endorsements, because the rules are clear and the volume is high. Submissions follow, then claims intake and renewals. Within months the whole operations team works with agents on every file, and your people are trained to run and extend them.
Everything is built in your accounts. The code, the data and the credentials stay yours.
The systems we work with
Agents work inside the policy administration and document systems you already run. At TIE they work inside Surefyre and query the federal SAFER database mid-process to catch carriers that re-register under a new DOT number to shed a bad safety record. The same pattern fits any platform with an API or a reliable inbox, including Guidewire, Duck Creek, Applied Epic and Vertafore.
Document reading is built for what insurers actually receive: ACORD forms, loss runs, driver licences photographed on a phone, and single files that mix several document types. A classifier works out what each page is from its contents, and a second model reads anything the first one cannot.
How to measure the impact
- Share of decisions made with no underwriter involved
- Queue-to-decision time for endorsements and submissions
- Entry and underwriting time per submission
- Quote turnaround and hit ratio with your retail agents
- Hours of queue time returned to the team
Case study · TIE
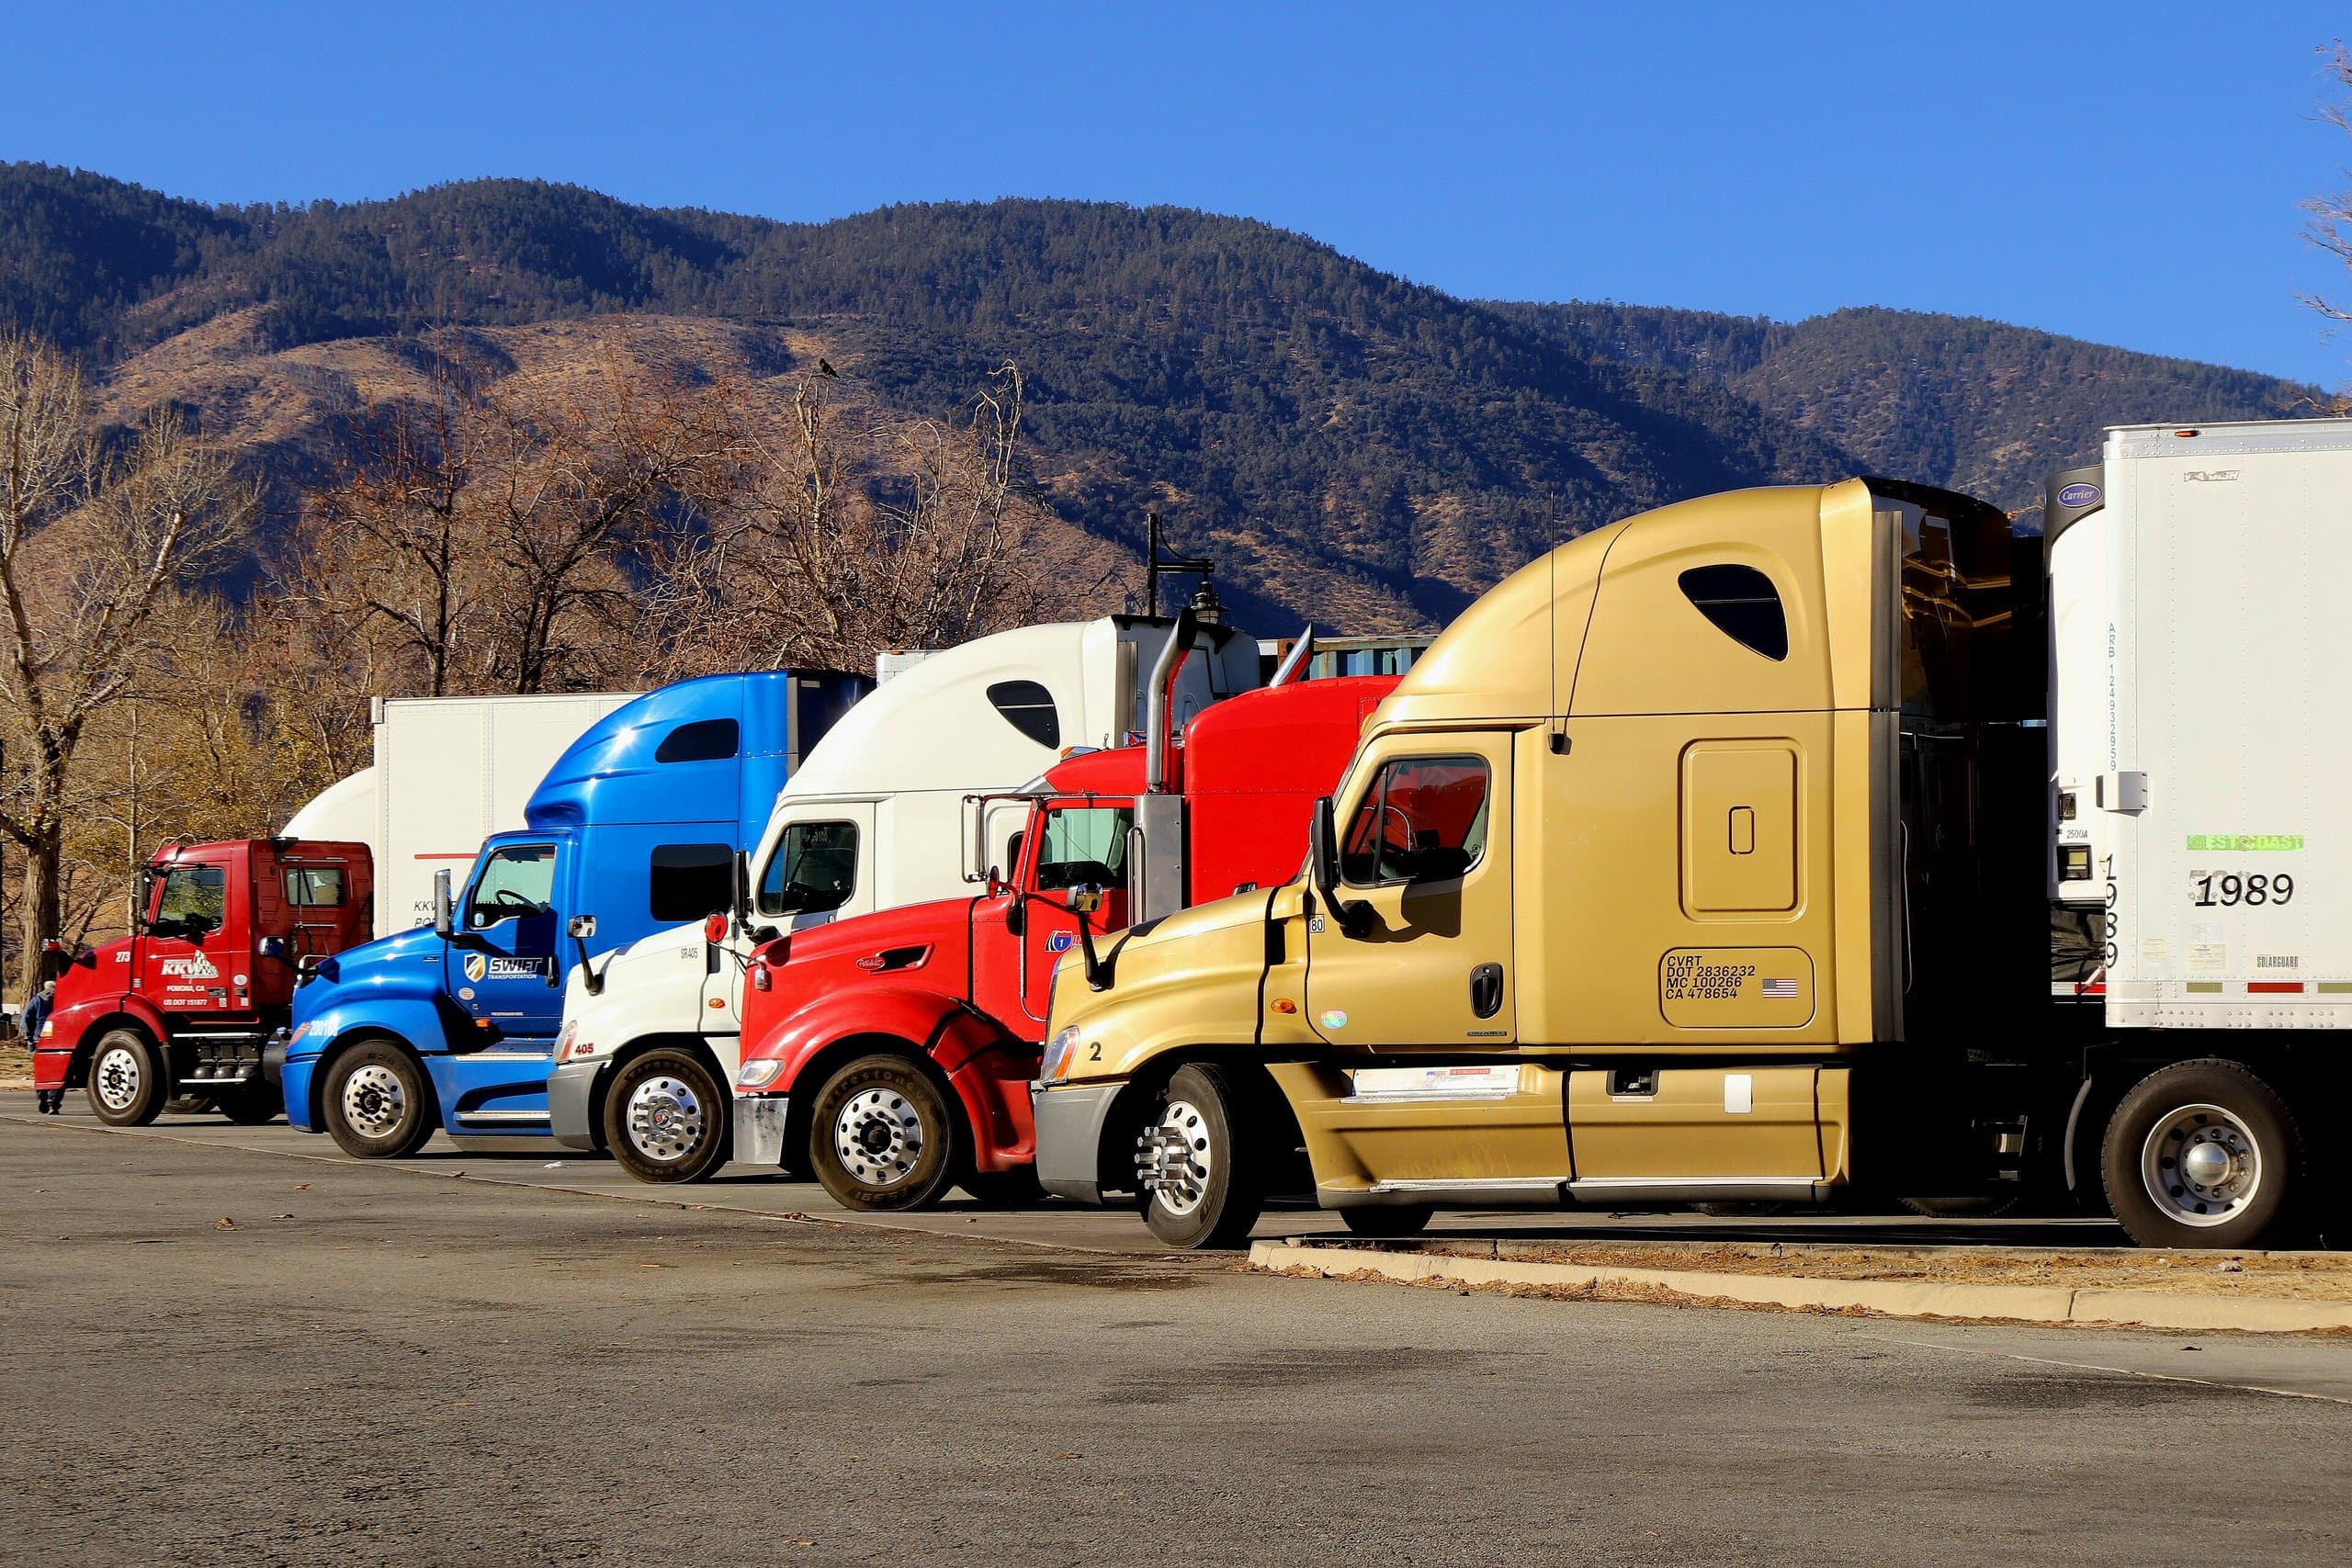
TIE decides transportation insurance endorsements in under a minute.
Native helped TIE, a US transportation insurance MGA, put agents on every submission and endorsement pack. They check each one and either decide it or hand the underwriter a pre-filled decision, and 74% of decisions now need no underwriter.
Frequently asked questions
What does an AI consultant do for an insurance company?
An AI consultant maps how work moves through your underwriting and operations teams, finds where files wait, and builds AI agents that do that work inside your systems. At Native the same team that maps the work builds the agents and stays until they run in production.
Can AI make underwriting decisions?
AI can settle decisions where the rules settle them, such as routine endorsements, and that is where most of the volume is. Decisions that need judgement go to an underwriter with the analysis already done. Where that line sits is agreed with your underwriting leads and written down.
How long does it take to put AI into production at an MGA or carrier?
The first agent is usually in production within weeks of starting. Whole departments, such as underwriting operations, run with agents on every file within months.
Who is accountable when an agent makes a decision?
Your team is. Each agent works within written authority, every action is logged with its reasoning, and a person can review or reverse any decision.
What should an insurer automate first?
Usually endorsements: the volume is high, the rules are clear, and the queue costs you service with agents. Submissions and claims intake tend to come next.